Dividend Reinvestment Plans (DRIPs): How They Work, Benefits and Risks
A dividend reinvestment plan, or DRIP, automatically uses each cash dividend you receive to buy more shares of the same stock or fund. Most large brokers do it for free and buy fractional shares, so every dollar goes back to work on the day it is paid.
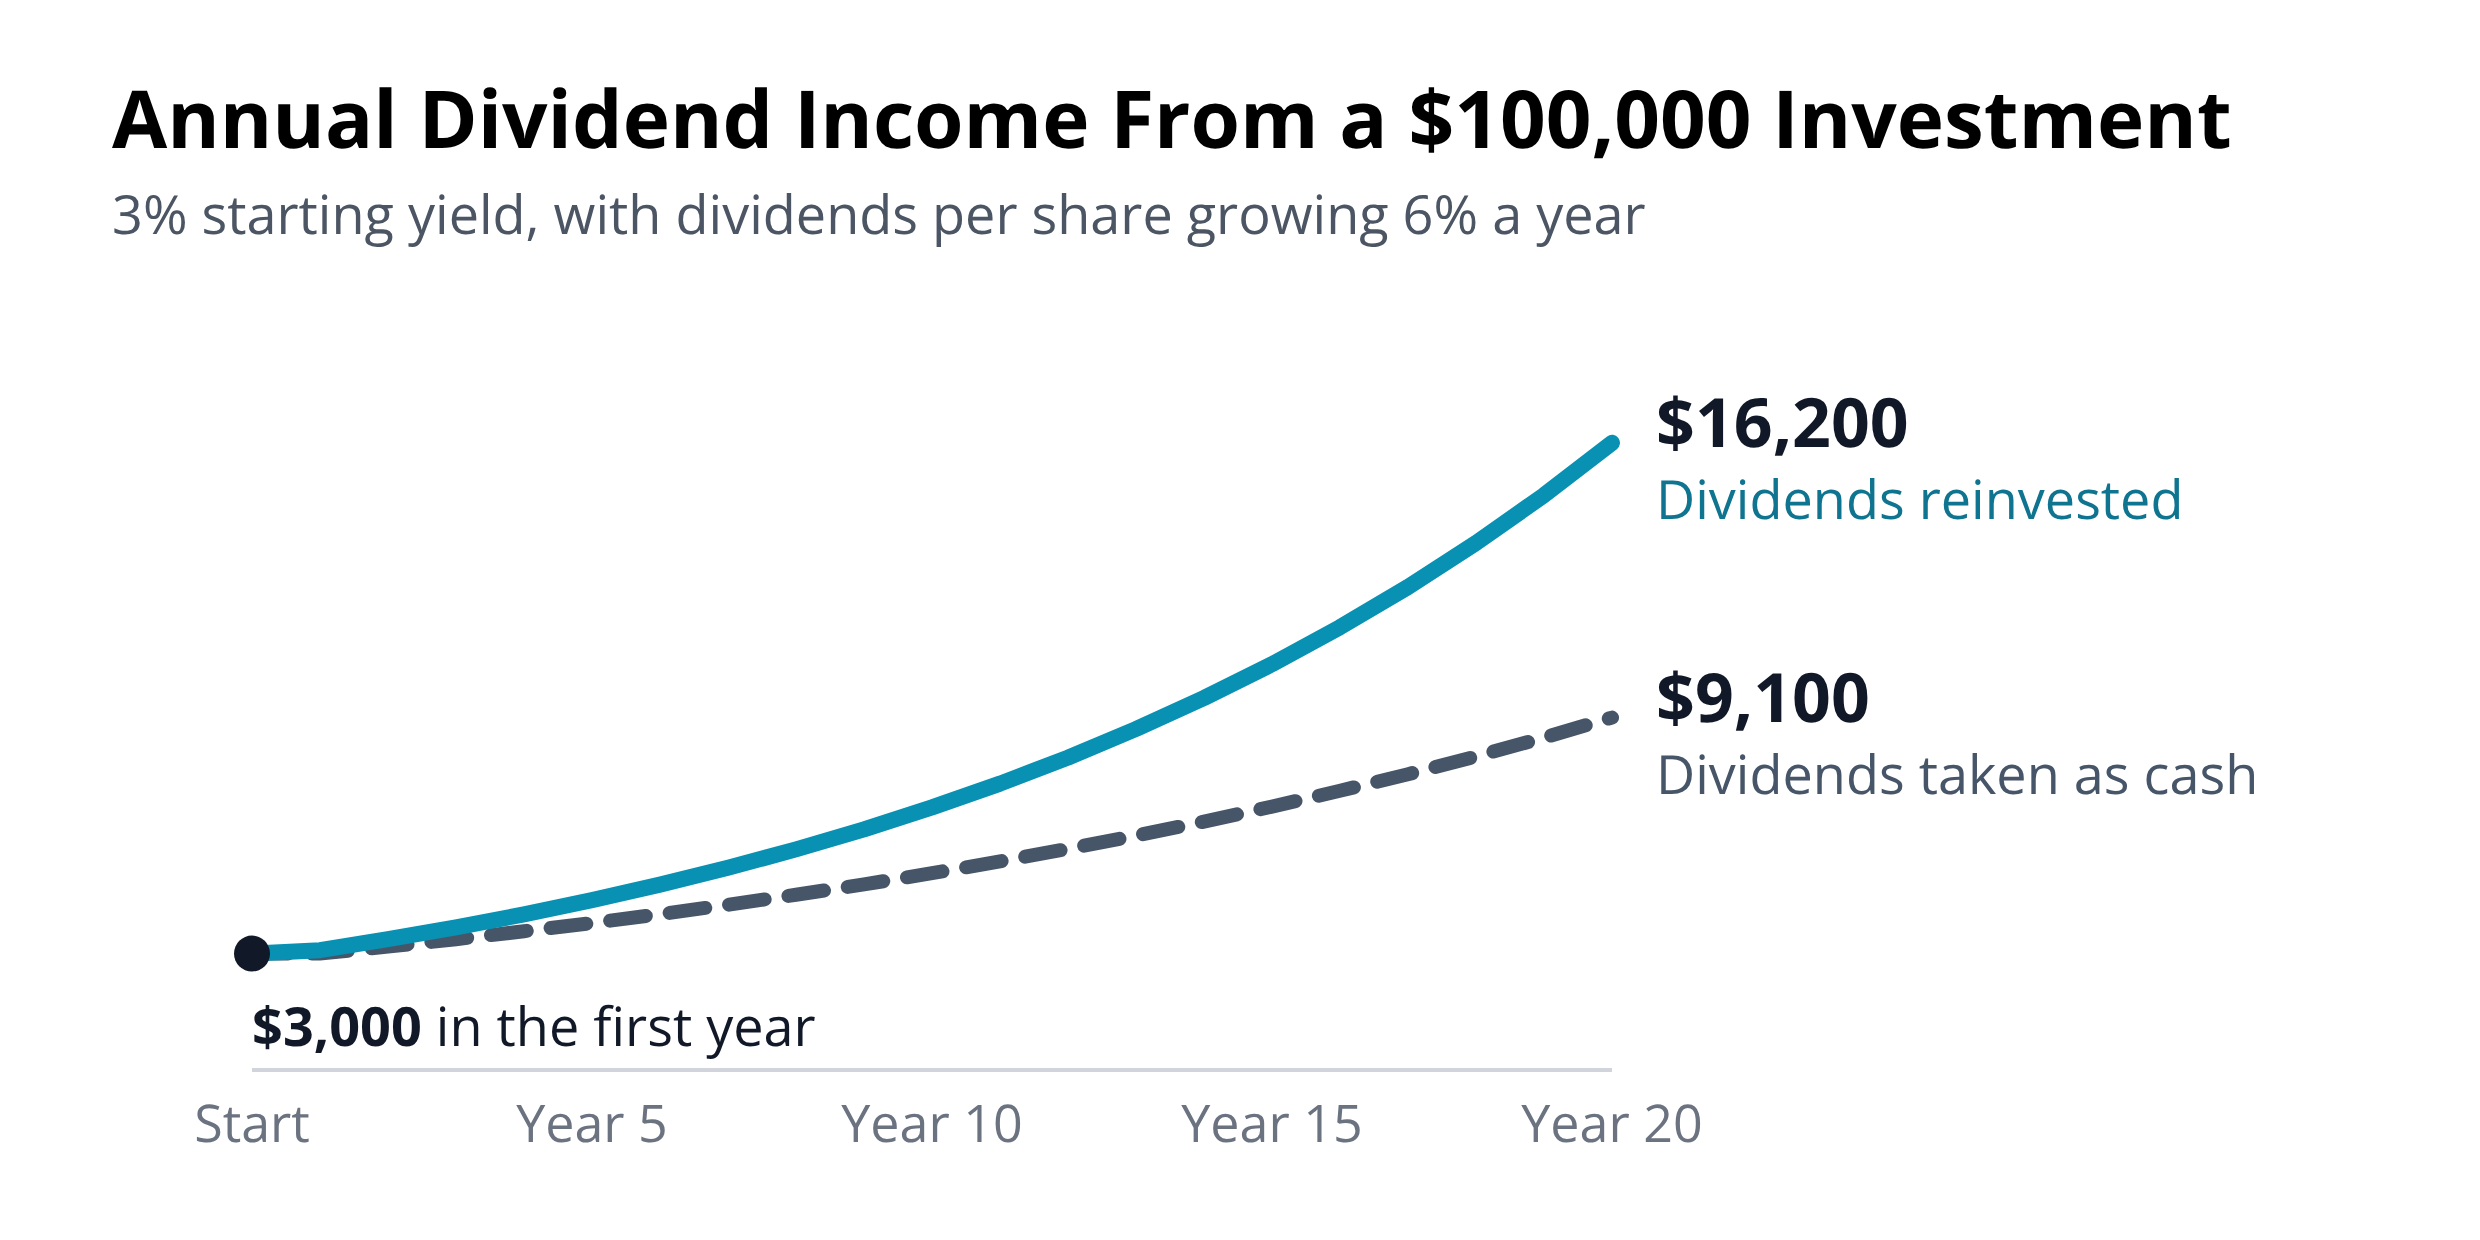
Reinvesting can lift a portfolio's income by about three-quarters over 20 years. In our example below, $100,000 earning a 3% yield with dividends growing 6% a year pays about $9,100 a year after two decades if you spend the dividends, and about $16,200 if you reinvest them.
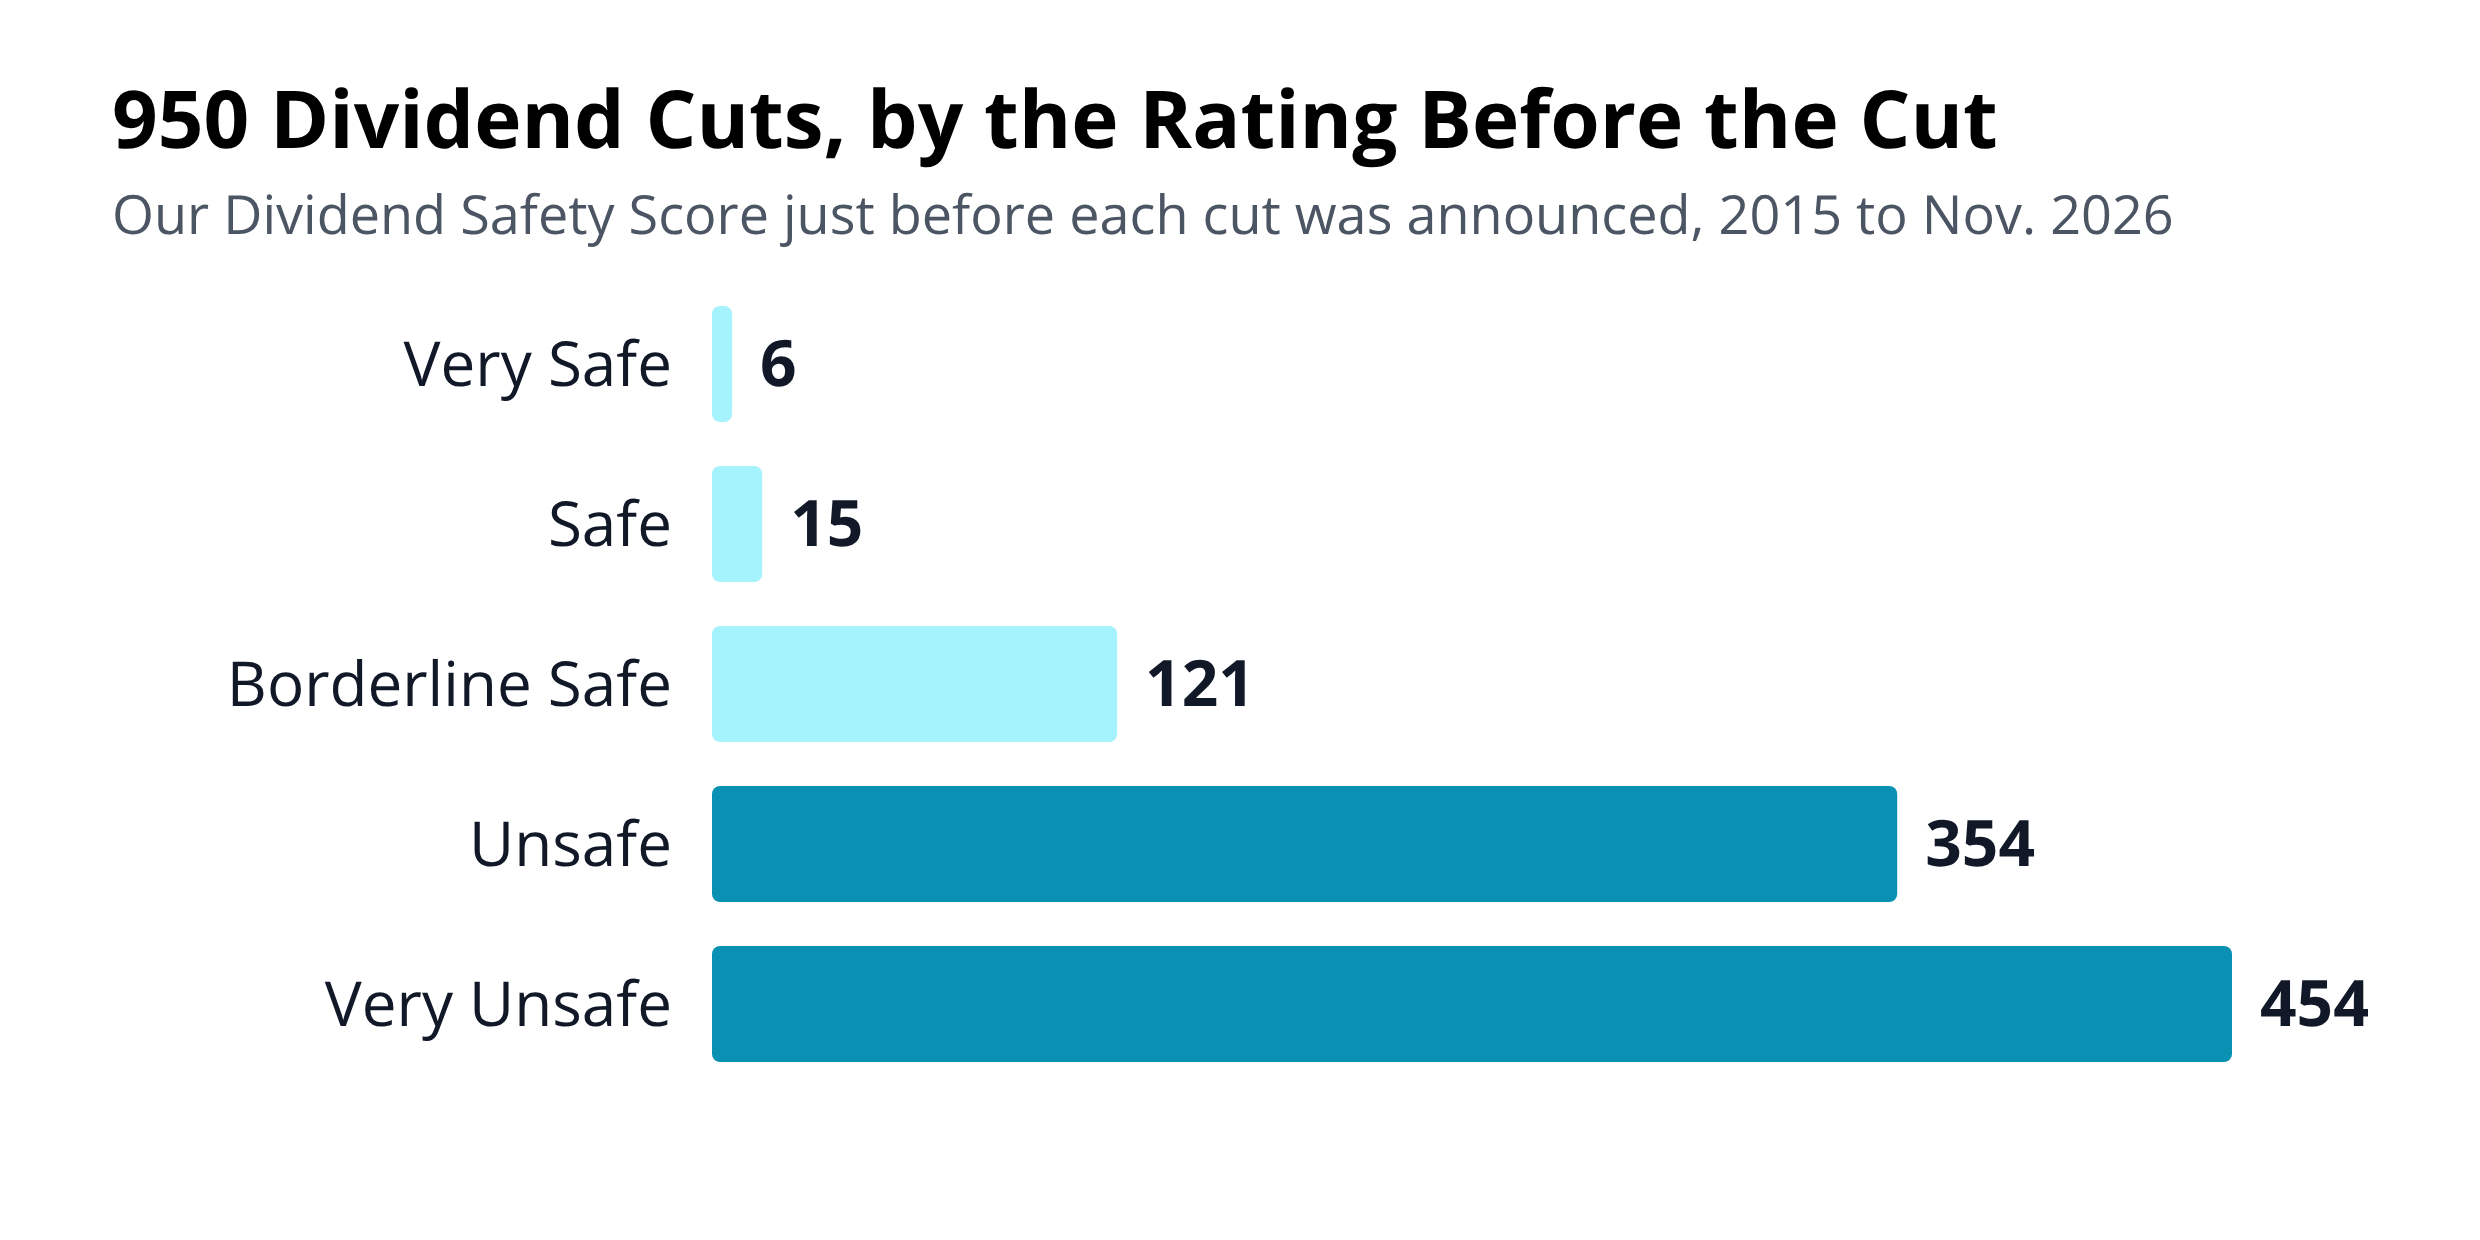
The catch is that a DRIP buys more of whatever you own, including the stocks most likely to cut. Of the 950 dividend cuts on our track record since 2015, 929 came from companies we rated below Safe beforehand.
What Is a Dividend Reinvestment Plan?
A DRIP replaces your cash dividend with new shares. If you own 100 shares of a $50 stock that pays a quarterly dividend of 50 cents, you would normally receive $50 in cash. With reinvestment turned on, that $50 buys one more share instead.
Next quarter you own 101 shares, so your dividend is a little larger, and it buys a little more. Over years and decades, that loop is what turns a steady dividend into a growing stream of income.
The purchase usually happens on the payment date, at or near that day's market price. It is the payment date that matters, not the ex-dividend date. Our guide to dividend dates explains the difference.
How to Reinvest Dividends: Broker vs. Company DRIPs
There are two main ways to reinvest, and for most investors the first is simpler.
Through your broker. Most large brokers will reinvest dividends on any eligible stock, ETF or closed-end fund you hold. Vanguard, for example, runs a no-fee, no-commission reinvestment program that credits fractional shares to three decimal places. You can usually turn it on for the whole account or for individual holdings.
Directly with the company. Many large companies run their own plans, usually through a transfer agent such as Computershare or Equiniti. Some let you buy shares directly with no broker, and a few sell plan shares at a small discount to the market price.
Company plans have drawbacks. Fees vary from plan to plan, selling can take days and cost more than a trade at a broker, and your holdings end up spread across separate accounts. Read the plan's prospectus for its fees before you enroll.
Funds work the same way. Most brokers reinvest ETF and mutual fund distributions automatically, and our guide to dividend ETFs vs. individual stocks covers the tradeoffs between the two.
How Reinvesting Dividends Compounds Your Income
Reinvesting adds a second engine to your income growth. Your companies raise their dividends, and each reinvested payment adds shares that collect those higher dividends.
To show the effect, we modeled $100,000 invested at a 3% yield, with dividends per share and the share price both growing 6% a year and dividends reinvested each quarter. Year one pays $3,000 either way.
By year 20, the investor who spends the dividends collects about $9,100 a year. The investor who reinvests collects about $16,200, roughly 78% more, because they now own about 1.8 times as many shares.
The investor who took cash isn't behind in every way. They collected about $110,000 of dividends along the way to spend or invest elsewhere. Reinvesting simply turns that cash into more shares and a bigger income later.
Time does most of the work. The two lines stay close for the first several years and pull apart quickly in the second decade, which is why reinvesting matters most for investors who are still years from needing the income.
Benefits of Dividend Reinvestment Plans
Beyond compounding, DRIPs offer a few practical advantages:
- No idle cash. Fractional shares mean the whole dividend is invested, even when it is smaller than the price of one share.
- Low or no cost. Broker DRIPs are usually free, and some company plans offer a small discount.
- Dollar cost averaging. You buy a little every quarter at whatever the price is, so you automatically buy more shares when prices are low.
- Fewer emotional decisions. Reinvestment happens whether markets are calm or panicking, which keeps you from sitting in cash waiting for the right moment.
That last point may be the most valuable. During a selloff, a DRIP keeps buying shares at lower prices and higher yields while many investors are frozen.
Dividend Reinvestment Plan Disadvantages
A DRIP's greatest strength, that it runs on autopilot, is also its main weakness. It buys more of each holding no matter the price or the risk.
It ignores valuation. A DRIP buys shares of an expensive stock as readily as a cheap one. If you would rather direct cash to your most undervalued holdings, taking dividends in cash gives you that choice. Our guide to dividend yield theory shows one way to judge value.
It adds shares fastest in the riskiest stocks. A stock yielding 10% reinvests into about 10% more shares each year, while a 2% yielder adds about 2%. Over time, a DRIP shifts your portfolio toward its highest yielders.
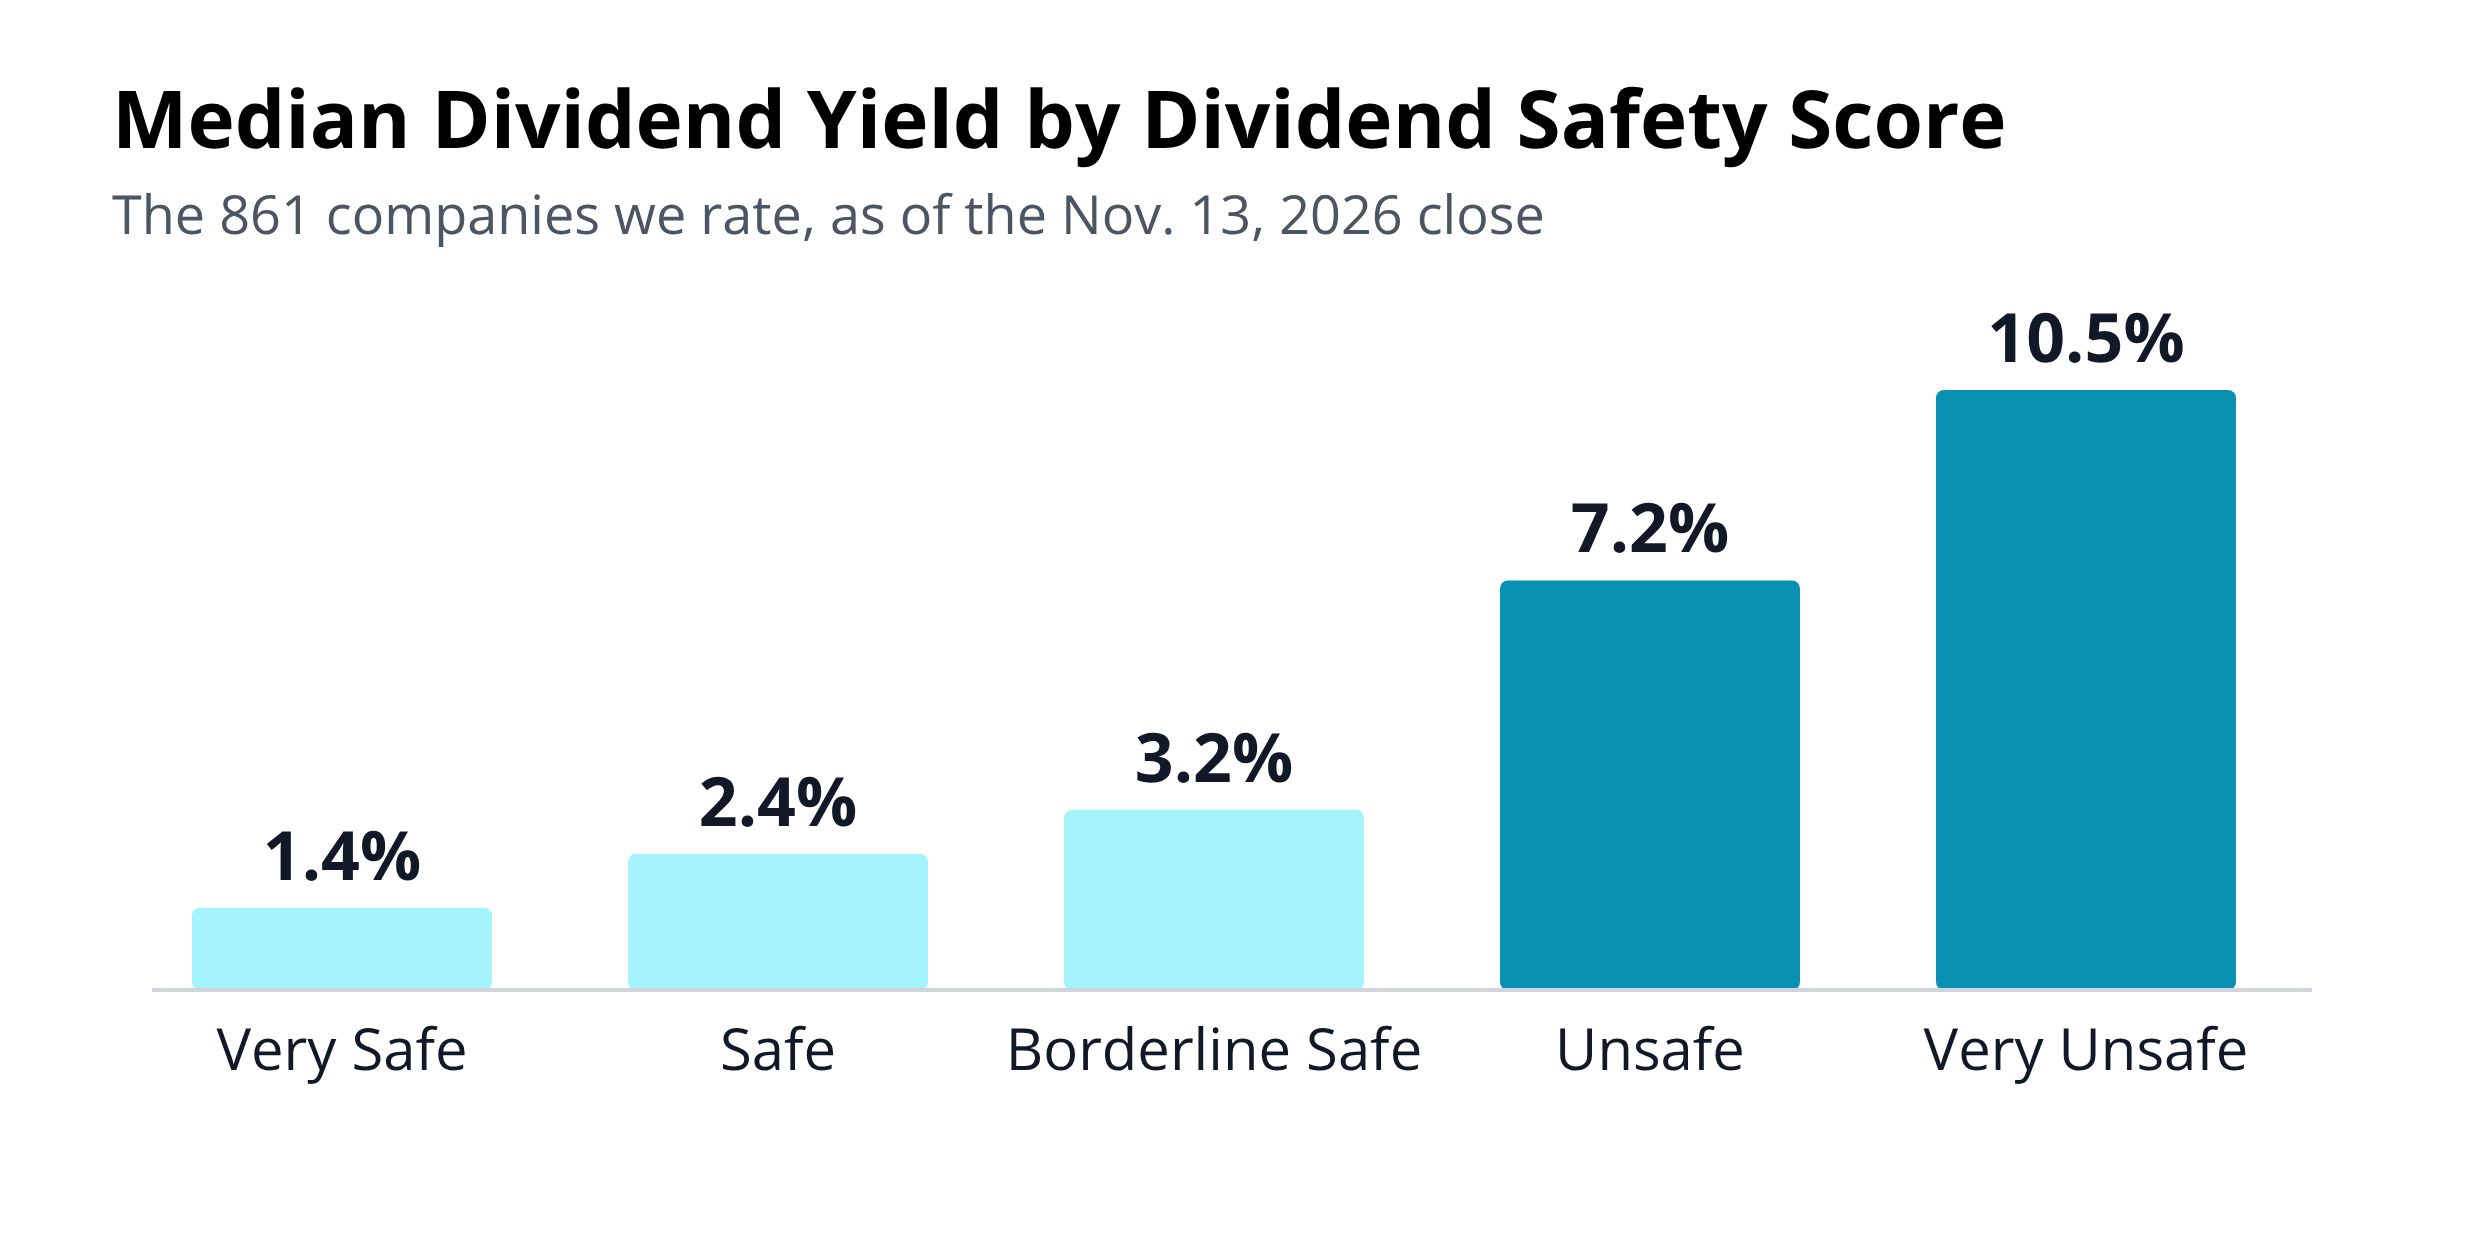
That matters because high yields and weak dividends tend to go together. Across the 861 companies we rate, the median stock with a Very Safe Dividend Safety Score yields 1.4%, while the median Very Unsafe stock yields 10.5%.
It creates more record keeping. Every reinvestment is a new purchase with its own price, so a holding reinvested for years can have dozens of small tax lots. Brokers now track this for you on most recent purchases, as the tax section below explains.
It doesn't pay your bills. Retirees who live on their dividends usually need the cash, and reinvesting it means selling shares later to raise money.
Why Dividend Safety Matters Before You Reinvest
A dividend cut hurts most in a DRIP. You keep buying more shares of a weakening business, often at falling prices, right up until the payout is reduced and those new shares earn less than you expected.
That is why we suggest reinvesting only into companies whose dividends look secure. Our Dividend Safety Score track record shows how rare cuts are among stronger companies. Of the 950 cuts since 2015, 808 came from companies we rated Unsafe or Very Unsafe before the cut. Only 21 came from companies rated Safe or Very Safe.
There are plenty of strong candidates. Of the 861 companies we rate, 412 earn a Safe or better Dividend Safety Score, and 305 of those have also raised their dividends for at least 10 straight years.
For holdings with weaker dividends, consider turning reinvestment off and directing that cash elsewhere. A higher yield on an Unsafe stock is not a reason to own more of it. Our guide to payout ratios explains one of the main signs we watch.
How Reinvested Dividends Are Taxed
Reinvesting doesn't change the tax bill in a taxable account. The IRS says reinvested dividends must be reported as income just like dividends you take in cash, so you can owe tax on money you never received in hand.
If a company plan lets you buy shares below market value, the IRS also treats the discount as dividend income. It says to report the fair market value of the extra shares on the payment date.
Each reinvestment also sets the cost basis of the shares it buys, usually their price on the day of purchase. Shares bought through a DRIP in recent years count as "covered securities," so your broker tracks that basis and reports it when you sell. The rules are in the IRS's frequently asked questions on stocks.
Inside an IRA, reinvesting works the same way, but IRA tax rules apply instead. Our guides to how dividends are taxed and traditional vs. Roth IRAs go into more detail.
Should You Reinvest Your Dividends?
For most investors who don't need the income yet, reinvesting dividends from safe, growing companies is a sound default. It keeps money working and takes timing decisions off the table.
Taking the cash makes more sense when you live on your dividends, when you want to rebuild a cash reserve, or when a holding has grown too large or its dividend looks shaky. Many investors split the difference by reinvesting only their strongest holdings.
We cover those situations in more depth in When Should I Reinvest Dividends?, and our guide to living off dividends covers the switch from reinvesting to spending.
How to Set Up a DRIP
At most brokers it takes a few minutes:
- Open your account settings and look for dividend reinvestment, often under account features or dividends.
- Choose whether to reinvest every eligible holding or pick them one by one.
- Turn reinvestment off for any holding you would rather not add to, such as a stock with a weak dividend or one that has grown too large.
- Check that new purchases also have reinvestment turned on, since some brokers apply the setting only to positions you already own.
For a company plan, start at the investor relations page, which usually links to the transfer agent that runs it. Review the fees and how to sell before you enroll.
Frequently Asked Questions
What is a dividend reinvestment plan (DRIP)?
A program that automatically uses your cash dividends to buy more shares of the same stock or fund. Brokers and many companies offer them, often with no fees and with fractional shares.
A program that automatically uses your cash dividends to buy more shares of the same stock or fund. Brokers and many companies offer them, often with no fees and with fractional shares.
What are the benefits of dividend reinvestment plans?
Faster compounding, no idle cash, low or no costs and automatic dollar cost averaging. In our example, reinvesting turned $3,000 of first-year income into about $16,200 by year 20, against about $9,100 for an investor who spent the dividends.
Faster compounding, no idle cash, low or no costs and automatic dollar cost averaging. In our example, reinvesting turned $3,000 of first-year income into about $16,200 by year 20, against about $9,100 for an investor who spent the dividends.
What are the disadvantages of dividend reinvestment plans?
A DRIP buys regardless of valuation, creates many small tax lots and adds shares fastest in the highest-yielding stocks, which tend to be the riskiest. The median Very Unsafe stock we rate yields 10.5%, against 1.4% for Very Safe stocks.
A DRIP buys regardless of valuation, creates many small tax lots and adds shares fastest in the highest-yielding stocks, which tend to be the riskiest. The median Very Unsafe stock we rate yields 10.5%, against 1.4% for Very Safe stocks.
Do you pay taxes on reinvested dividends?
Yes, in a taxable account. The IRS says reinvested dividends are reported as income just like cash dividends, and a discount on plan shares counts as dividend income too.
Yes, in a taxable account. The IRS says reinvested dividends are reported as income just like cash dividends, and a discount on plan shares counts as dividend income too.
Can you reinvest dividends from ETFs?
Yes. Most brokers reinvest ETF distributions the same way they reinvest stock dividends. Vanguard's program, for example, covers stocks, ETFs and closed-end funds.
Yes. Most brokers reinvest ETF distributions the same way they reinvest stock dividends. Vanguard's program, for example, covers stocks, ETFs and closed-end funds.
Are dividend reinvestment plans free?
Most broker DRIPs are. Vanguard, for example, charges no fee or commission to reinvest. Company plans run by transfer agents set their own fees, so check the plan prospectus.
Most broker DRIPs are. Vanguard, for example, charges no fee or commission to reinvest. Company plans run by transfer agents set their own fees, so check the plan prospectus.
Is reinvesting dividends a good idea for risky stocks?
Usually not. Of the 950 dividend cuts on our track record since 2015, 929 came from companies rated below Safe beforehand. Reinvesting into a stock heading for a cut means buying more just before its income drops.
Usually not. Of the 950 dividend cuts on our track record since 2015, 929 came from companies rated below Safe beforehand. Reinvesting into a stock heading for a cut means buying more just before its income drops.
Want to see the Dividend Safety Score of every stock you reinvest into, and how your income could grow with reinvestment on or off? Our portfolio tools show both. Take a look at our demo.